 Aave
Aave connects crypto suppliers and borrowers through collateral-backed lending
Aave lets users supply crypto to lending markets and borrow available assets against eligible collateral. Smart contracts account for deposits, interest, and debt, while market rules determine borrowing capacity. Supplying alone doesn't require taking a loan. Borrowing creates an obligation whose value changes with accrued interest and asset prices. Access depends on the selected network, supported tokens, and the account's collateral settings. Even sufficient collateral can't overcome unavailable liquidity or a binding market limit. The practical distinction is between an amount the account can support, an amount the market can provide, and a debt the borrower can maintain.
Key takeaway: Borrowing capacity reflects eligible collateral, while available liquidity and market restrictions determine whether a loan can actually execute.
A borrow request before and after confirmation
With eligible collateral already supplied, an ordinary borrow transfers the requested asset and adds debt to the account. Consider a V3 account with no existing debt whose owner wants to inspect the proposed loan before committing. The connected account, network, and market must match the collateral position.
The account's supplied balance must qualify as collateral for the intended borrowing. A token balance alone doesn't establish this. The proposed amount must also fit the account's borrowing capacity, the asset's borrowing permissions, and available liquidity.
If the available liquidity is smaller than expected, the unsigned request can be reduced or abandoned. Reducing it only works if the revised request satisfies every other condition. Adding more collateral in a different asset won't replenish the asset the pool lacks, so increasing that deposit doesn't resolve this liquidity shortage.
| Stage | Account or transaction state | Condition for proceeding |
|---|---|---|
| Identify the position | The wallet shows the existing supply in the selected market. | The network and account must match the collateral position. |
| Check collateral eligibility | Eligible supplied assets contribute borrowing capacity. | Collateral settings and borrowing restrictions must permit the asset. |
| Review the proposed amount | The request remains unsubmitted. | Capacity, available liquidity, and applicable caps must allow it. |
| Authorize and submit | The signed transaction requests the borrow. | Protocol conditions must still hold when execution occurs. |
| Reconcile the account | A successful borrow delivers tokens and records debt. | The receipt and resulting balances must match the intended action. |
Before signing and submitting the borrow transaction, the owner can stop without creating that new debt. This doesn't reverse the earlier supply. Once submitted, cancellation isn't assured; once executed, closing the obligation requires repayment rather than withdrawing consent.
A successful receipt, received tokens, and the corresponding debt establish completion. A wallet signature alone doesn't. If the interface appears unchanged, the transaction's execution status and the selected account need resolving before another borrow is submitted.
What limits the amount you can borrow?
Eligible collateral establishes borrowing capacity, while liquidity, asset permissions, and market limits can reduce the amount actually available.
Collateral value and borrowing power
Loan-to-value, or LTV, controls how much borrowing an asset's collateral value supports. Existing debt already consumes part of that capacity. Supplying an asset and enabling it as collateral are separate conditions; a market can accept deposits without allowing those deposits to support borrowing. Collateral parameters belong to the selected market, so the same token can have different rules elsewhere.
Reserve liquidity and caps
A reserve is a token's lending allocation within a V3 pool. Its borrow cap limits total borrowing across that reserve, including other accounts. Available liquidity is the amount the pool can deliver. Either constraint can bind before an individual reaches their collateral limit. Supply caps separately restrict additional deposits. Governance can change these settings, so a remembered maximum isn't a permanent entitlement.
Health factor and liquidation exposure
Health factor measures how much liquidation-adjusted collateral covers outstanding debt, and it changes after the original borrowing decision.
The liquidation boundary
For a V3 position with debt, health factor equals total collateral value multiplied by its weighted average liquidation threshold, divided by total debt value. The calculation uses protocol valuations. A V3 borrowing position becomes eligible for liquidation when its health factor falls below 1. This boundary differs from the LTV limit governing new borrowing.
Movement after borrowing
Falling collateral prices reduce coverage. Rising prices of borrowed assets increase the debt's value, and accrued interest increases the amount owed. Assets moving together can reduce relative price risk, but that relationship can break. A health factor above the boundary describes the position at that moment; it doesn't reserve time to react.
Collateral taken during liquidation
A liquidator repays eligible debt and receives collateral with a liquidation bonus. This reduces the borrower's remaining collateral. The amount eligible for liquidation depends on the applicable implementation and position conditions. Repayment or additional eligible collateral can improve health, but a pending transaction doesn't prevent another transaction from executing first.
Supply balances and withdrawal liquidity
Suppliers earn interest when their assets support borrowing, without needing to create debt themselves. V3 represents supplied assets through aTokens, whose balances reflect accrued supply interest. Withdrawal exchanges that claim for underlying assets and requires sufficient unborrowed liquidity. Collateral supporting debt also faces account-health restrictions. Repaying debt can remove a collateral constraint, but it doesn't guarantee enough liquidity for every withdrawal. A growing supply balance therefore differs from immediately withdrawable funds.
Interest and transaction costs
Borrowing costs accumulate over time, while transaction fees arise when the account submits operations to the network. Variable interest rates respond to utilization and configured rate parameters. Supplier interest comes from borrowing activity after the protocol's applicable allocation. Comparing supply and borrow percentages alone misses differences in balances, asset values, and holding periods.
Token supply or repayment may also require spending authorization. An approval transaction can incur a network fee; supported permit signatures provide another authorization method. Approval grants a contract permission to transfer tokens within its allowance. It doesn't itself prove that a supply or repayment completed.
Market versions and specialized borrowing settings
The selected implementation determines which settings apply, so familiar terminology doesn't make positions interchangeable across markets.
V3 efficiency mode
Efficiency mode, or E-mode, applies category-specific collateral parameters and borrowing permissions. Eligible combinations can receive greater borrowing power. Its categories define which assets can support the position and which assets it can borrow. Correlation is relevant to the risk assumptions, but it doesn't prevent price divergence.
V3 isolation and siloed borrowing
Isolation mode restricts borrowing against designated collateral to approved assets and a debt ceiling. Other collateral can't simply be added to the same isolated position. Siloed borrowing imposes a different restriction: borrowing a designated asset prevents simultaneous borrowing of other assets in that pool. These controls constrain different parts of an account.
V4 Hubs and Spokes
V4 organizes liquidity through Hubs and Spokes. A Hub manages shared liquidity and accounting; Spokes handle particular lending configurations and user positions. Hub limits restrict how much liquidity a Spoke can draw, alongside local risk settings. V4 also includes a collateral-dependent borrowing risk premium. Its architecture doesn't make V3 pool settings applicable to V4 positions.
Delegated credit and flash loans
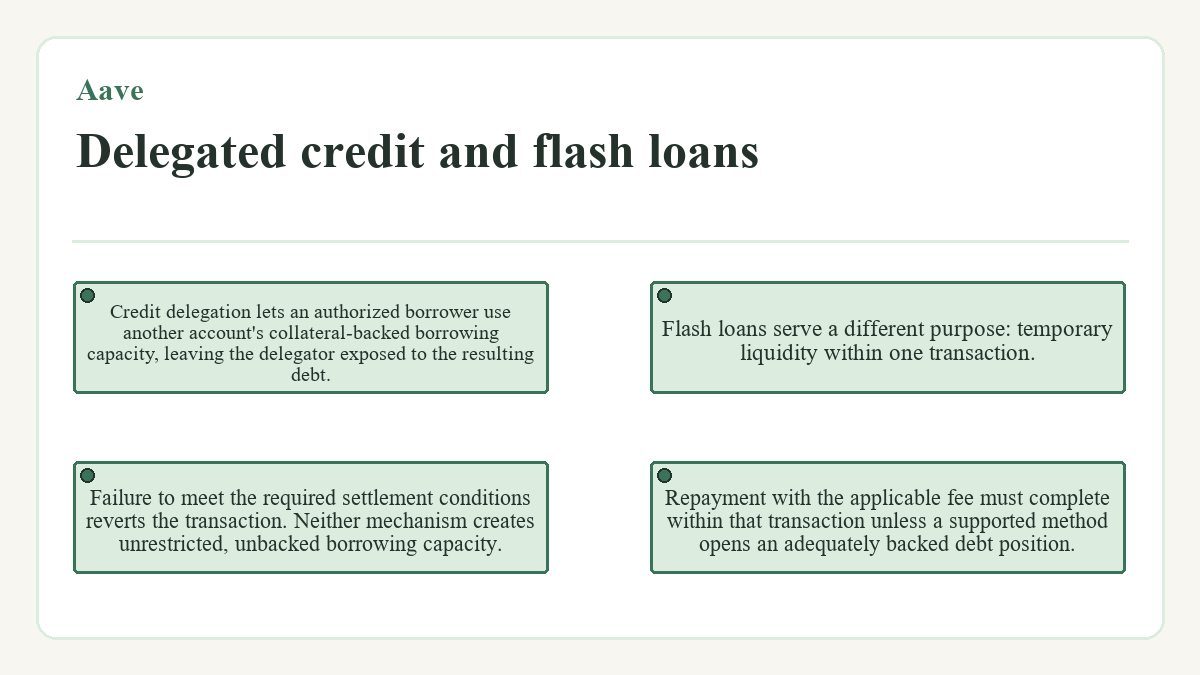
Credit delegation lets an authorized borrower use another account's collateral-backed borrowing capacity, leaving the delegator exposed to the resulting debt. Flash loans serve a different purpose: temporary liquidity within one transaction. Repayment with the applicable fee must complete within that transaction unless a supported method opens an adequately backed debt position. Failure to meet the required settlement conditions reverts the transaction. Neither mechanism creates unrestricted, unbacked borrowing capacity.
Does borrowing fit better than selling the collateral?
Borrowing retains exposure to collateral while creating debt; selling reduces that exposure without creating a lending obligation. The choice turns on whether retaining the asset justifies interest costs and liquidation exposure. Supplied collateral also depends on contracts, token behavior, and price oracles. A valuation failure or loss of collateral liquidity can damage the position even without another borrow.
Network congestion can delay repayment or collateral transactions when timing matters. Bridged assets introduce dependencies on the mechanism backing their representation, and a recognizable ticker doesn't remove those dependencies.
Repayment reduces debt and can free collateral, subject to remaining obligations and withdrawal liquidity. Selling avoids ongoing debt maintenance but gives up exposure to the amount sold. Supplying without borrowing is another distinct choice: it seeks lending income while retaining the market's contract and liquidity risks.
Practical questions about Aave
Do I need AAVE tokens to supply or borrow?
Holding AAVE isn't a general requirement for supplying supported assets or borrowing against eligible collateral. AAVE is the protocol's governance token. An ordinary lending position instead needs the relevant assets, sufficient borrowing capacity when taking debt, and the network resources required to execute transactions. Holding the governance token doesn't replace those conditions.
How long can a V3 borrowing position stay open?
A standard V3 borrowing position can remain open while it satisfies the protocol's collateral requirements. It doesn't follow a conventional fixed installment schedule. Interest continues accruing, and changing asset values or risk parameters can affect its health before the borrower chooses to repay. Partial repayment reduces the outstanding obligation.
Can another address repay my loan?
V3 supports repayment on behalf of another account. The payer supplies the required repayment asset and authorizes its transfer, while the specified borrower's debt decreases. Paying someone else's debt doesn't automatically transfer their collateral or ownership of their account to the payer. The repayment method and beneficiary address determine whose obligation is reduced.
What happens to my debt when I disconnect my wallet?
Disconnecting a wallet from an interface leaves its onchain borrowing position in place. The debt belongs to the account recorded by the protocol, so interest and liquidation conditions continue independently of the browser connection. Disconnecting also doesn't submit a repayment transaction. Closing the debt requires a successful protocol operation.
Does collateral in one V3 market cover borrowing in another?
A V3 pool assesses borrowing against the collateral held within that pool's account state. A supply position in another pool doesn't automatically contribute capacity, even when the same wallet controls both positions. Network selection and market selection therefore affect which collateral, debt, and available liquidity the interface displays.
Are aTokens the same as AAVE?
aTokens represent supplied assets and their accrued supply interest in V3, while AAVE is a governance token. Each aToken corresponds to a particular underlying asset in a market. Its balance records a supply claim rather than an allocation of governance tokens. That claim remains subject to the market's withdrawal and collateral conditions.